The short answer: photograph first, protect second, call third
When a roof leak damages the inside of a home, three things matter in order. Take photos before anything is moved, take reasonable steps to stop more damage, and contact your insurer promptly. Policies differ, so read yours or ask the insurer which parts of the loss it covers.
This guide is general information about records, not legal or insurance advice. It does not tell you whether a claim will be paid, because only your policy and your insurer can answer that.
The aim is simple. A claim goes more smoothly when the story is clear: when the leak began, what it touched, what you did about it and what the damage looked like before cleanup.
What to document, and how
| What | How to capture it | Why it helps |
|---|---|---|
| The roof leak source | Photos from the ground and inside the attic, if it is safe to enter | Shows where the water entered |
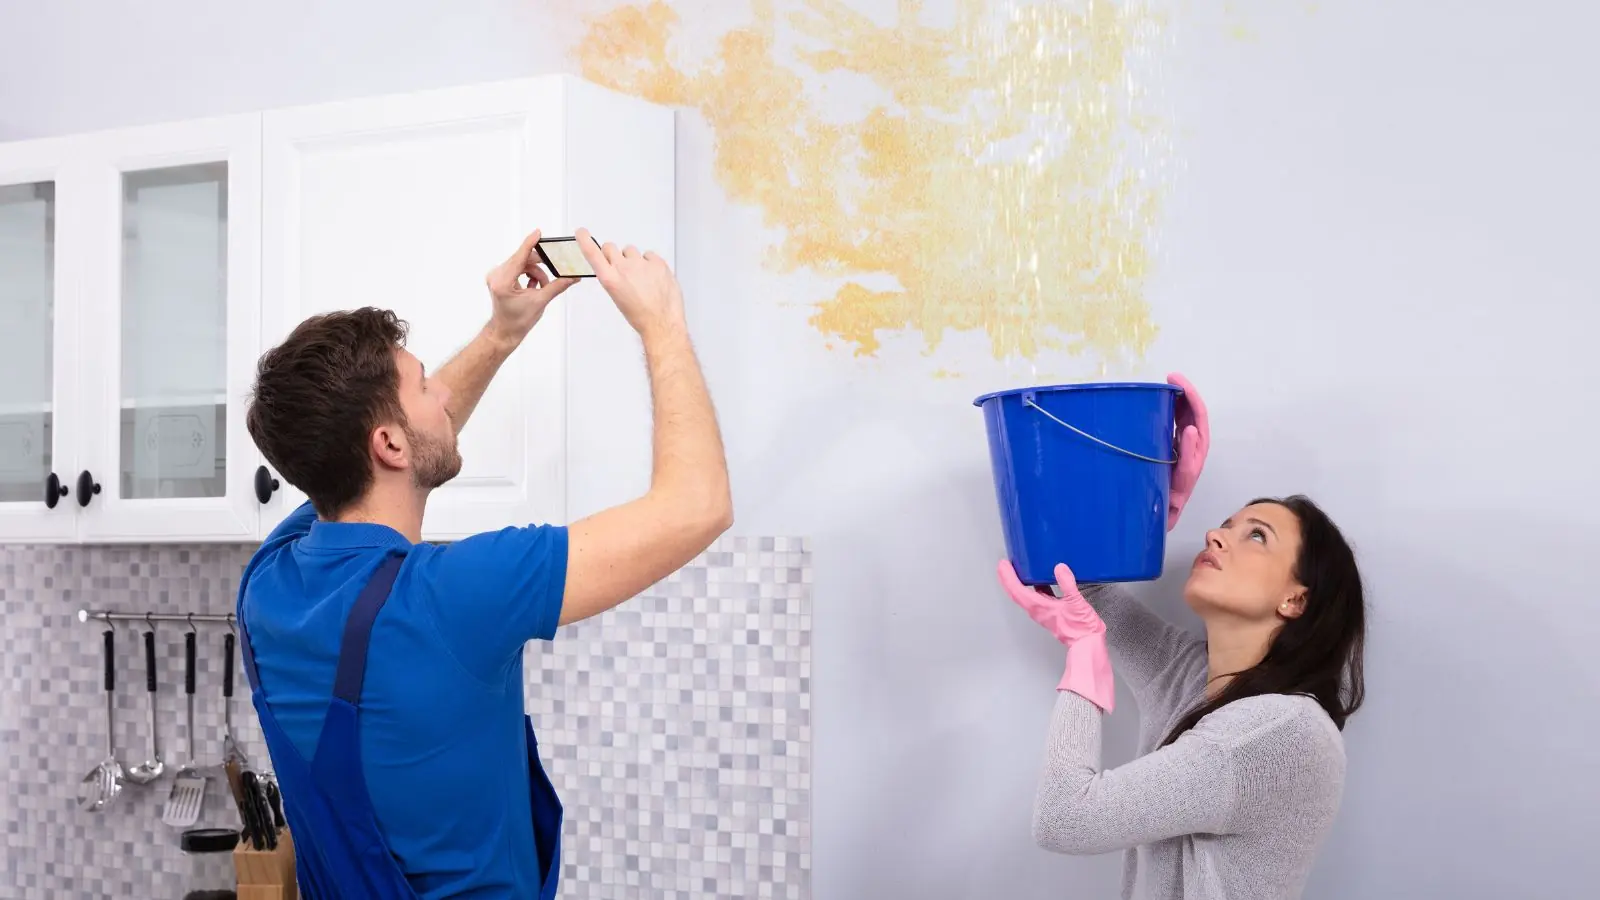
| Wet ceilings and walls | Wide shot of each room, then close shots of stains and sags | Shows the extent before cleanup |
| Damaged belongings | One photo of each item and a written list with rough age | Supports a contents list |
| Time stamps | Keep the phone's date and time on every photo and video | Establishes when you noticed |
| Moisture readings | Ask the crew for dated meter readings and equipment logs | Shows how wet the building was and how drying progressed |
| Receipts | Keep every receipt for tarps, buckets and emergency repairs | Shows your reasonable steps |
Take reasonable steps to stop more damage
Many policies expect a homeowner to take reasonable steps to prevent further damage, such as covering an opening or moving belongings. Check your policy language for that duty. Keep receipts for tarps or other temporary measures, because those are the proof of what you did.
Stay off a wet or steep roof. A temporary tarp should be placed by someone equipped to work at height, since a fall is a bigger loss than any ceiling.
Inside the house, move furniture away from wet areas, set out buckets and keep people out from under sagging ceilings. If a crew is coming, leave wet material in place until it has been photographed.
Why drying records matter
A roof leak often soaks insulation, ceiling drywall and the tops of walls before a stain appears. To find that hidden water, crews scan with thermal imaging cameras and probe with moisture meters, then log readings as drying proceeds. Those logs show what was wet and when it dried.
That is the practical work of water mitigation, and it is worth starting while the claim is being sorted out, because wet insulation does not wait for paperwork. Delay is how a roof leak turns into a mold problem.
Before any work begins, the crew walks you through the scope and how the price is built. The usual drivers are the count of wet rooms, the materials involved, the days of drying and the rebuild that comes after.
Repairs come after drying
Fixing the roof, replacing wet drywall and painting are separate steps from drying. The interior rebuild falls under water damage repair, and it is best left until readings show the building is dry.
Keep the invoices from each phase separate. A drying invoice, a roof invoice and a rebuild invoice tell a clearer story than one lump sum.
Cover and exclusions in plain terms
A roof that fails in a single storm is usually treated differently from one that has wept for years. Policies commonly respond to the first and push back on the second, with wear and neglect the typical sticking points. Rising floodwater is a separate matter and usually needs its own flood policy. Whether storm-driven rain through the roof counts as covered depends on the wording, so ask your insurer.
Never assume. If you are unsure, ask your insurer to explain the category in writing, and keep the answer with your records.
Colton note: what the state insurance guide says
The California Department of Insurance residential property claims guide says to tell your insurer about water damage right away. It also states that flood falls outside homeowners coverage and calls for a separate policy, that other water damage is generally covered, and that mold resulting from a covered loss may be covered.
If you suspect mold, the guide says to get in touch with the adjuster at once. The department's flood insurance guide adds that a flood policy has a 30-day waiting period before it takes effect, so waiting for a storm to buy coverage does not work.
The guides do not give a specific claim deadline in days on the pages checked, so ask your insurer how long you have to file. Keep that written answer with your photos and receipts.
If you live in a nearby town
Crews also respond in Rialto and in Bloomington, which is unincorporated. The documentation steps do not change, and neither does the principle that your policy is the source of truth.
Frequently asked questions
Call your insurer first, or at the same time, and ask what temporary steps they expect. A tarp is usually reasonable, while a full roof replacement may need approval. Keep receipts and photos.
A crew's logs and photos are useful evidence of what was wet and how drying went, but the insurer decides what counts. Ask the insurer what documents it needs, and provide the crew's records on request.
Per the state insurance department, mold that comes from a covered loss may itself be covered, and it advises calling your adjuster at once if you suspect it. Your own policy governs, so read its mold language.
As soon as you find it. The state guide says to report water damage right away. Winter storms can reveal a leak days later, so mention when you first saw the stain.
Gradual damage is often treated differently from sudden damage, and may not be covered. Document what you see, do not guess about when it began, and ask your insurer how it classifies the loss.